Industry Trends
←
All blog posts
The Distribution Guide
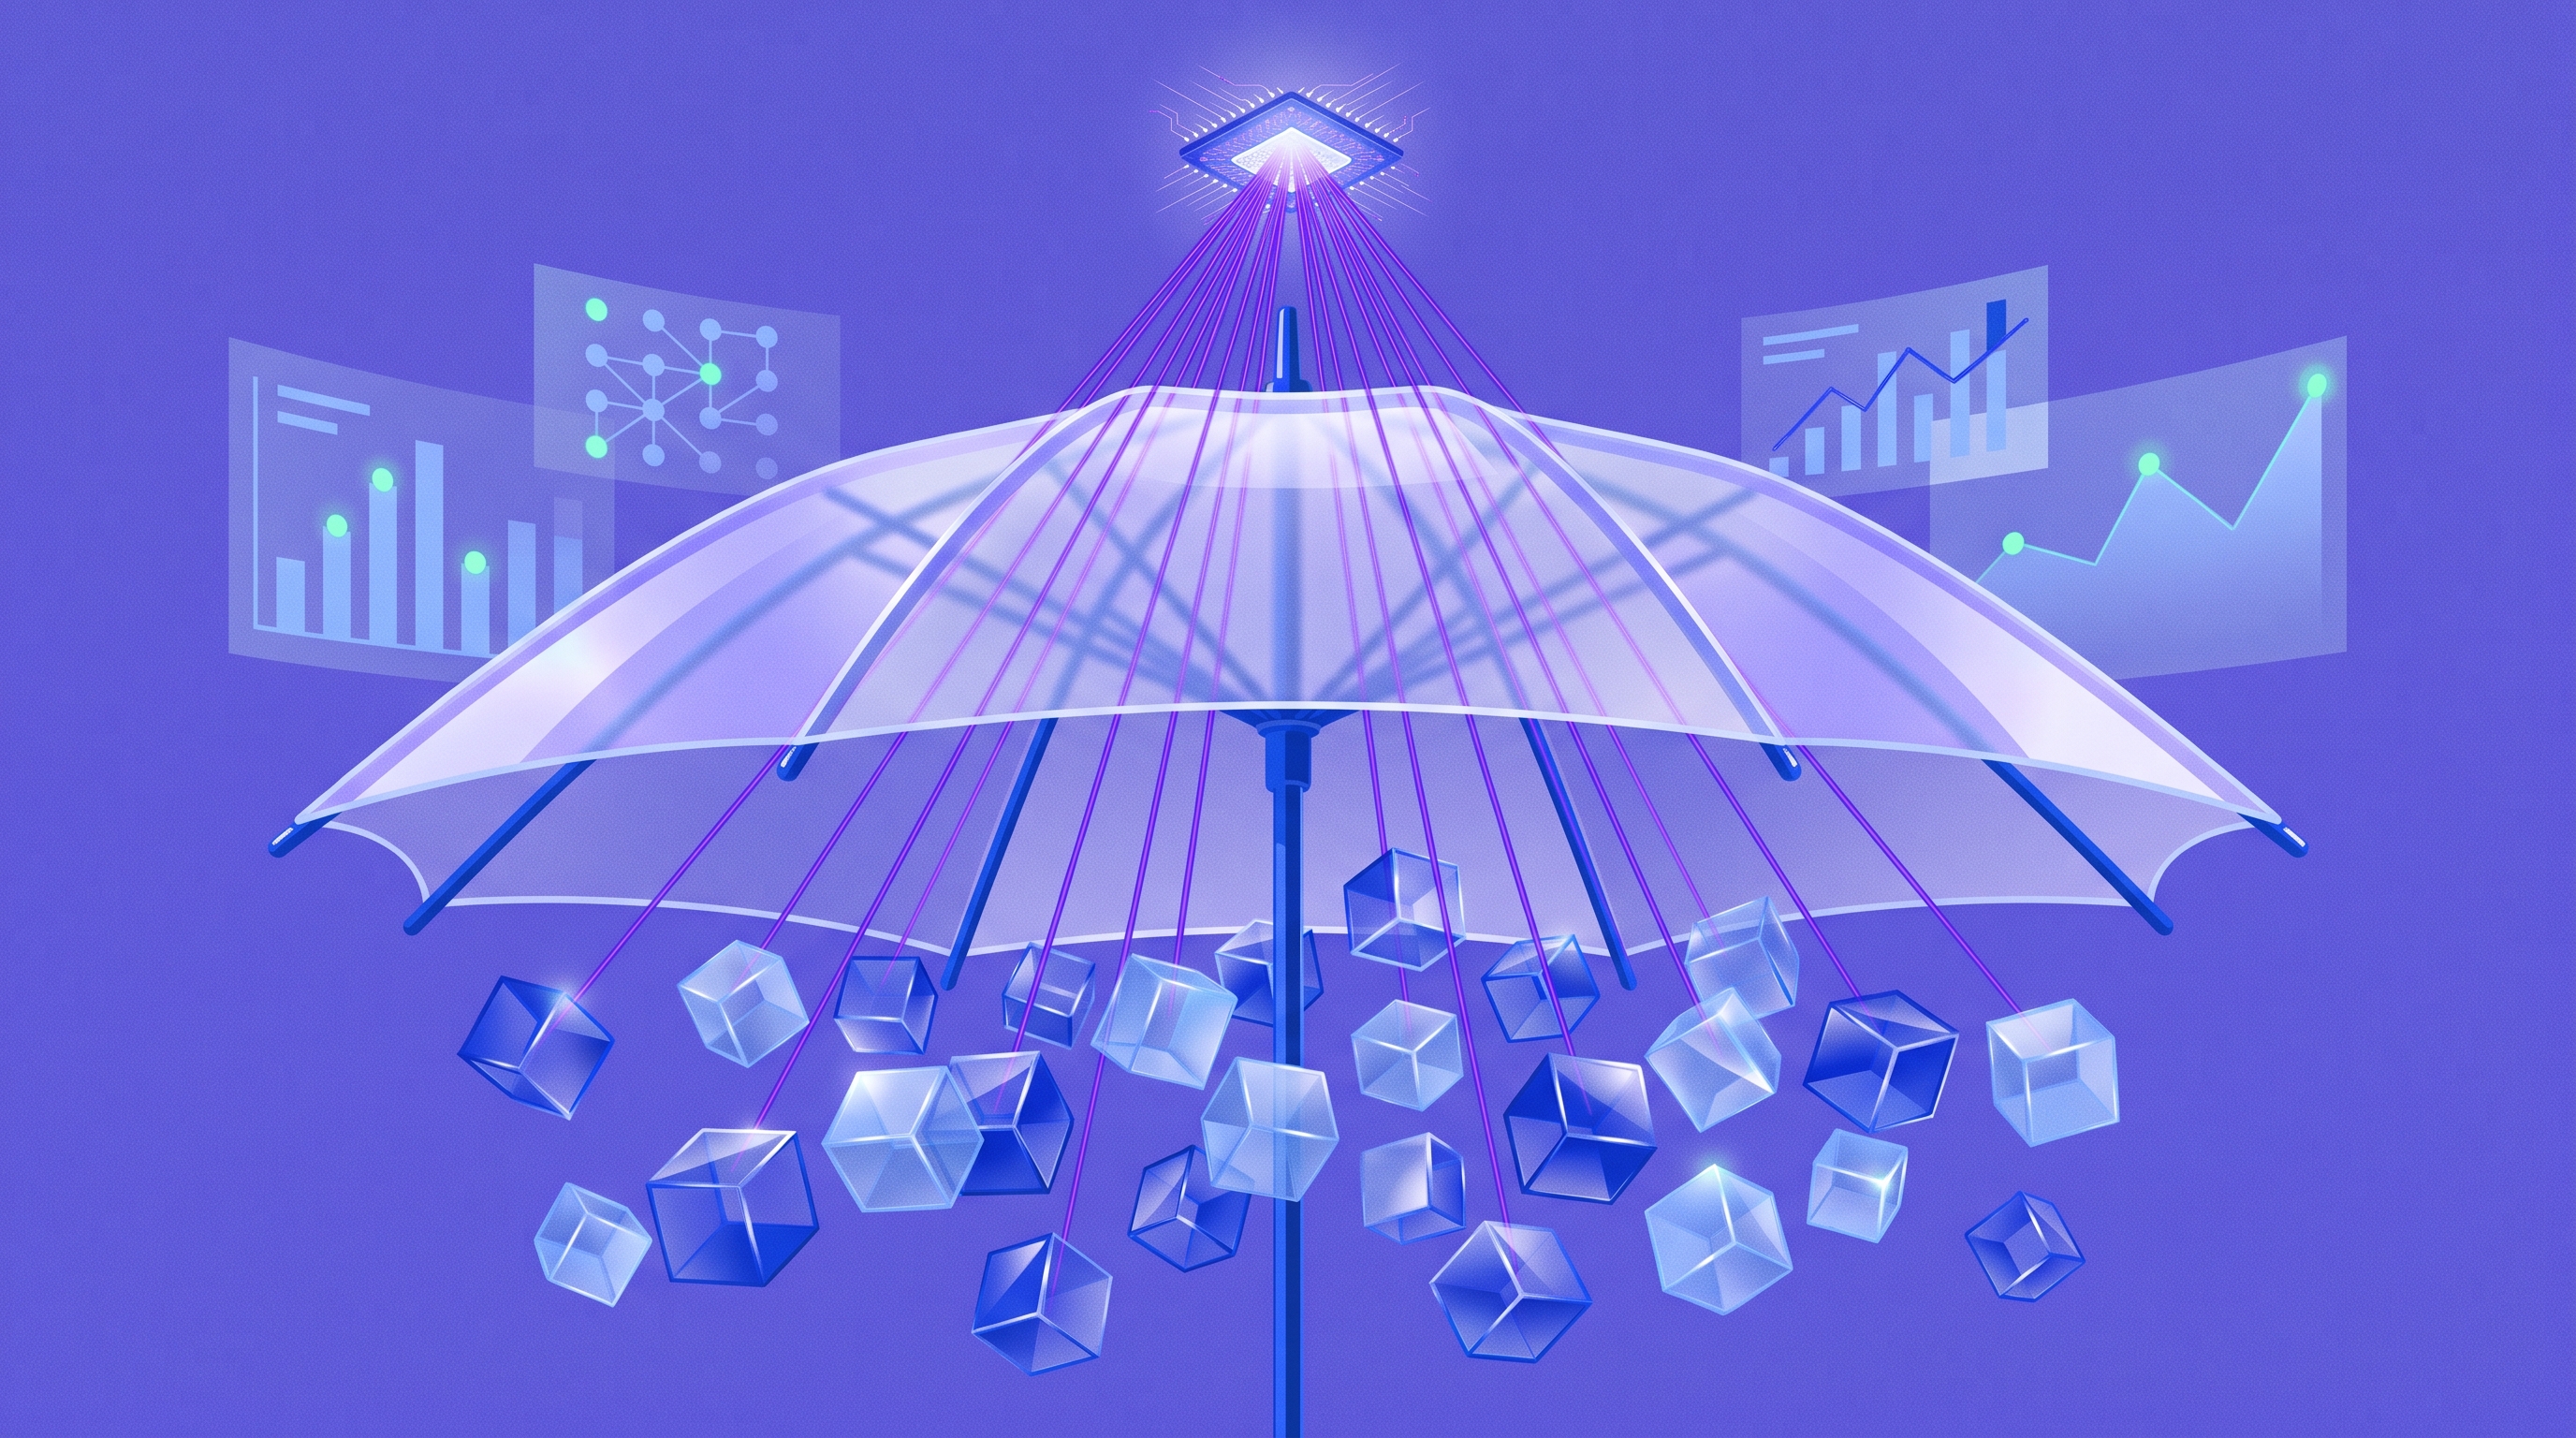
A company uses an AI agent to handle customer enquiries. One day, the agent gives out the wrong information and a customer suffers a financial loss. They file a claim. Which policy responds? General liability, errors and omissions, cyber? Any of them?
That question, which until recently sounded theoretical, moved to centre stage this week.
Silent AI exposure is the risk that traditional policies, such as general liability, errors and omissions, cyber or D&O, end up covering losses caused by AI systems without that risk having been considered when the wording was drafted or the premium was priced. The issue gained momentum after Anthropic, the company behind Claude, warned in its IPO filing that a severe AI incident could exceed the capacity of the insurance market.
Here is what happened, why it worries the industry and what brokers can review with their clients.
On 26 October 2026, Anthropic filed its registration statement with the SEC, the US securities regulator, ahead of its stock market listing. Among the risks it lists, several directly concern insurance:
This is not a loss that has happened. It is a potential risk that one of the leading AI companies has put in writing in its financial disclosures. And for the industry, that matters.
"It's a signal."
Rian Wickens, Head of Cyber & IT Liability, Liberty (Asia Pacific), speaking to Insurance Business
It is the situation in which a policy that was never designed with AI in mind ends up responding to a loss caused by it. Not because the wording says so, but because it does not exclude it either.
The industry has been here before, and remembers it well:
"We've been here before on silent risk in insurance policies with terrorism, pandemic and cyber. AI won't be any different."
Rian Wickens, Liberty, speaking to Insurance Business
These are the policies where AI exposure could be sitting without being named:
The answer will always depend on how the loss occurred, the terms agreed and the exclusions. Using AI does not mean a company is covered, nor that it is not. The problem is that many wordings do not yet make it clear.
For two reasons: pricing and accumulation.
Pricing. If a policy responds to a risk that was never considered, the premium does not reflect it. And because there is still very little claims history for AI, it is hard to estimate how often these losses will happen and how much they will cost. Morningstar DBRS, the credit rating agency, warns that this can lead to inaccurate pricing, reserve uncertainty and earnings volatility.
Accumulation. Insurers spread risk across many different policyholders. But if thousands of companies rely on the same AI model, a single failure could trigger claims across all of them at once, under different policies and with a single cause.
"Anthropic's IPO puts the AI insurance protection gap in focus."
Marcos Alvarez, Head of Global Insurance, Morningstar DBRS, in Reinsurance News
That is why the agency recommends that insurers measure their total exposure, review their policy limits and check that their reinsurance and capital can absorb a scenario like this.
Yes, but not all of it. That is the view of much of the market:
"The fundamentals of insurance as a risk transfer strategy for AI risk remain robust", but "it cannot be assumed that all AI exposures will be insurable".
Andrew Hill, Global FINEX AI Risk Strategic Leader, WTW, speaking to Insurance Business
Some analysts believe the most pressing problem is not the large AI developers, but their customers. Evercore ISI analysts, quoted in Reinsurance News, put it this way: a more immediate issue for the industry will be "latent claims against companies that deploy the technology", which may already be sitting in policies that have been written.
For brokers, this is the key point: the risk is not only in Silicon Valley, it is in the client portfolio you already have.
There is no need to wait for a major loss. These questions help uncover exposures that currently go unnoticed:
These questions do not replace a review of the policy wording, nor do they guarantee any particular cover. But they help you get ahead, spot gaps and add value as an adviser in a conversation your clients do not yet know they need to have.
AI offers the industry many opportunities, from greater efficiency to better customer service. But more and more businesses depend on the same models and providers, and that creates new dependencies and new liabilities.
When one of the companies building this technology acknowledges limits to the protection available, that is not bad news for insurance. It is an opportunity to do the job well: identify the risk, understand how it could materialise and know who it affects. That is where the broker's role as an adviser matters more than ever.
Sources: Anthropic's S-1 filing with the SEC, Insurance Business and Reinsurance News, 27 October 2026.
The AI platform that automates operations for brokerages, agencies, and bancassurance.


© 2026 Foliume SA. All rights reserved.